

Zoom has been treading water for the past six months, recording a small return of 3.6% while holding steady at $93.79. The stock also fell short of the S&P 500’s 8.9% gain during that period.
Is now the time to buy Zoom, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Zoom Will Underperform?
We don’t have much confidence in Zoom. Here are three reasons you should be careful with ZM, plus one stock we’d rather own.
1. Weak ARR Points to Soft Demand
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
Zoom’s ARR came in at $5.11 billion in Q2, and over the last four quarters, its year-on-year growth averaged 5%. This performance was underwhelming and suggests that increasing competition is causing challenges in securing longer-term commitments. 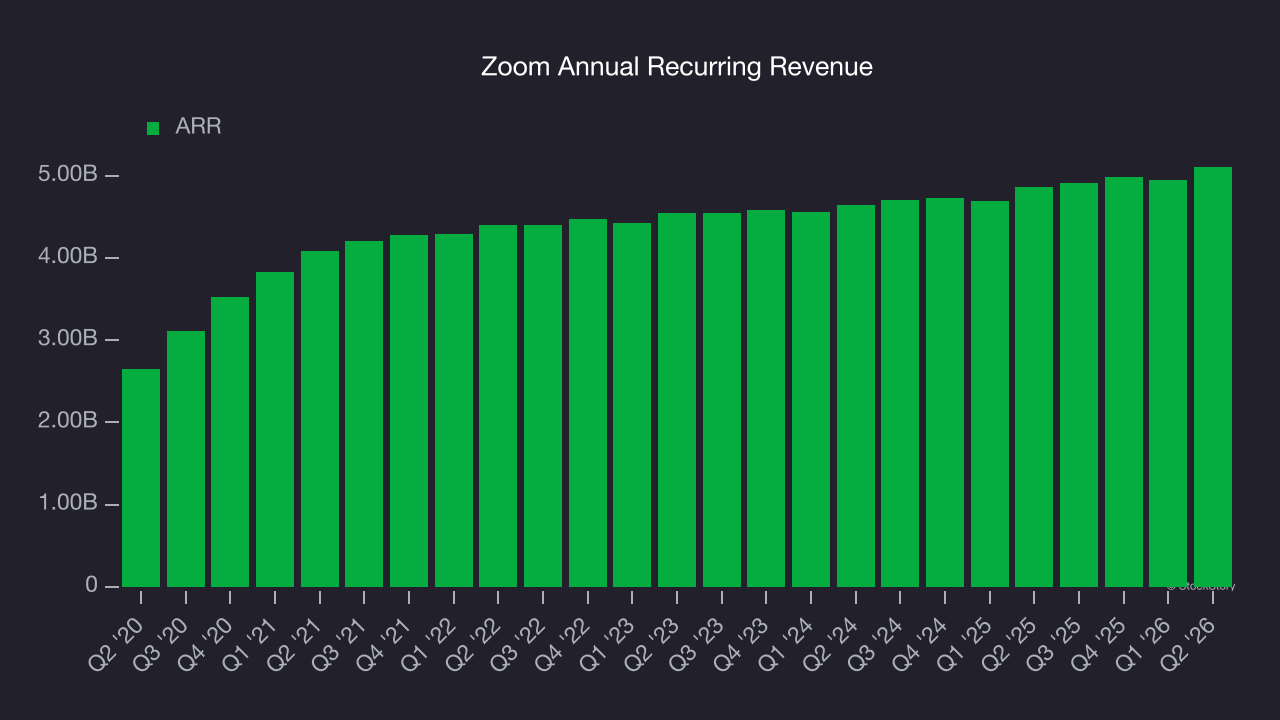
2. Customer Churn Hurts Long-Term Outlook
One of the best parts about the software-as-a-service business model (and a reason why they trade at high valuation multiples) is that customers typically spend more on a company’s products and services over time.
Zoom’s net revenue retention rate, a key performance metric measuring how much money existing customers from a year ago are spending today, was 99% in Q2. This means Zoom’s revenue would’ve decreased by 1% over the last 12 months if it didn’t win any new customers (remember that net revenue retention can be well over 100%).
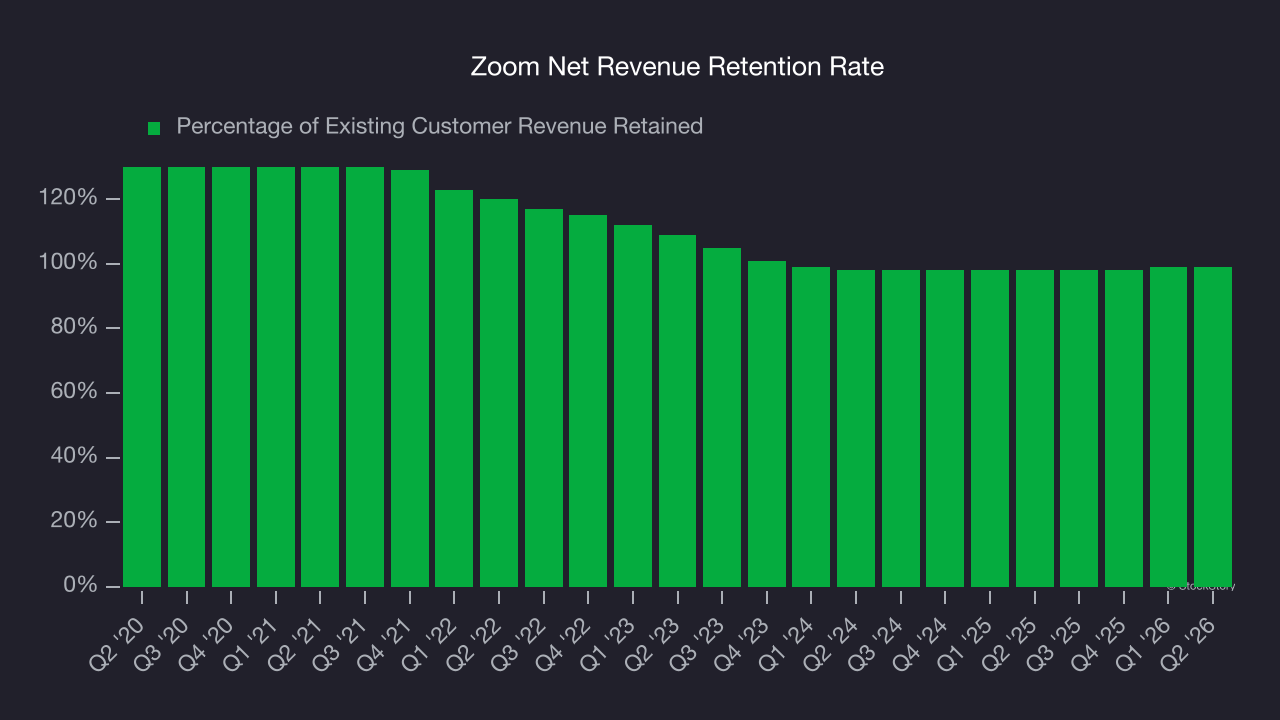
Zoom has a weak net retention rate, signaling that some customers aren’t satisfied with its products, leading to lost contracts and revenue streams.
3. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Zoom’s revenue to rise by 3.9%, close to its 6.5% annualized growth for the past five years. This projection is underwhelming and implies its newer products and services will not accelerate its top-line performance yet.
Final Judgment
We cheer for all companies solving complex business issues, but in the case of Zoom, we’ll be cheering from the sidelines. With its shares lagging the market recently, the stock trades at 5.7× forward price-to-sales (or $93.79 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - you can find more timely opportunities elsewhere. We’d suggest looking at an all-weather company that owns household favorite Taco Bell.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.